If you can’t afford major repairs before selling your California home, you have four paths. You can sell as-is, list with seller credits, finance the repairs, or make only low-cost fixes. You can sell the property as-is to a cash buyer. In an as-is sale, you make no repairs, and the buyer accepts the home exactly as it stands.
You can list it on the open market and negotiate seller credits so the buyer handles repairs after closing. You can finance the repairs yourself through a home equity line of credit or personal loan. Or you can make specific low-cost improvements that improve buyer perception without touching the big-ticket items. Whichever path you choose, count closing costs when you compare what you will net.
The right path depends on three things. They are how much work the home needs, how fast you must sell, and whether a lender will finance it as-is. Closing costs are a key part of the net proceeds calculation when choosing a selling path.
This guide covers which issues make a home unfinanceable, how to price a home that needs work, and how to net the most. It draws on the 300+ California transactions Quick Home Offers® has closed since 2013.

What to Do If You Can’t Afford Home Repairs Before Selling — Quick Answer
If you cannot afford repairs before selling, an as-is sale is typically the fastest path to closing. In an as-is sale, you make no repairs and the buyer takes the home in its current condition. Cash buyers purchase the property as-is, with no inspection or lender approval required. They can often close in 7 to 10 days, which helps sellers who need to sell fast. Keep in mind, buyers of as-is properties often account for the cost of repairs they will need to undertake after purchase.
You can also list the home as is on the open market with a real estate agent, though most traditional buyers will request an inspection and may ask for repair credits or concessions. This route is best for properties that need minor or cosmetic repairs.
Financing the repairs with a home equity line of credit (HELOC) works if you have equity in the home and the repairs are moderate.
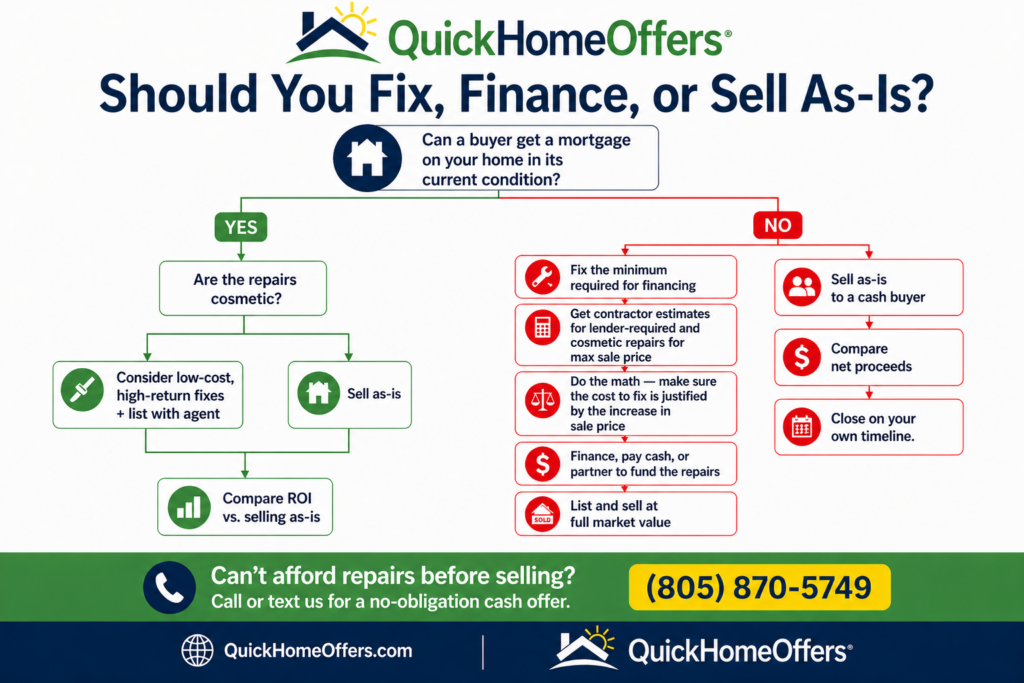
Some issues stop a buyer from getting a mortgage: a damaged roof, foundation problems, failing electrical or plumbing, missing flooring or windows, or code violations. With any of them, only cash buyers and investors can buy the home, whichever path you choose.
Is Your Home Financeable? Why This Matters Before You Decide
A home is financeable if a buyer can get a mortgage on it in its current condition. Answer that question before you choose how to sell, because a no changes everything.
Traditional lenders require a home to meet minimum property standards before they approve a loan. When a home fails those standards, the buyer’s loan is denied and the sale falls apart, however motivated the buyer is.
Lenders also require the buyer to carry homeowner’s insurance, and many insurance companies will not write a policy on a home with a damaged roof, outdated electrical, active plumbing leaks, unresolved structural issues, or code violations. If the home cannot be insured, it cannot be financed.
The most common issues that block financing and insurance include:
- a roof with active leaks
- foundation issues or settling that affect the structural integrity
- outdated or unsafe electrical systems, like knob-and-tube, and recalled electrical panels
- plumbing issues or failures, like corroded galvanized pipes and damaged sewer lines
- no working heater
- missing flooring
- broken windows
- fire or water damage, or mold issues
- code violations
If your home has one of these issues and you cannot fix it, only cash buyers and investors can buy it. They do not rely on lender or insurance approval. That is true whether you list with an agent or not. You can still list with an agent, but only cash buyers can close. You would pay 5% to 6% in commissions to reach a buyer you could have contacted directly.
Before you commit to any path, get cash offers first. Contact at least three cash buyers, compare what they will pay for the property in its current condition, and use those numbers as your baseline. If the cash offers are close to what you would net after agent commissions and months of carrying costs on the open market, selling directly saves you time and money.
If your home’s core systems are intact and the issues are cosmetic — outdated finishes, worn carpet, a kitchen that needs updating — your buyer pool is broader, and you have more options.
We have sold two properties to Quick Home Offers this year…
We have sold two properties to Quick Home Offers this year, dealing mostly with Adam Justiniano. Adam is very professional and made the entire process smooth both times.
Can’t afford to fix it before selling? You don’t have to.
We’ll Call You Within 1 Business Day
Enter your number. We’ll walk through your options — whether you sell to us or not. No fees. No obligation. Serving California since 2013.
Low-Cost Improvements That Actually Help — and What Improvements to Skip
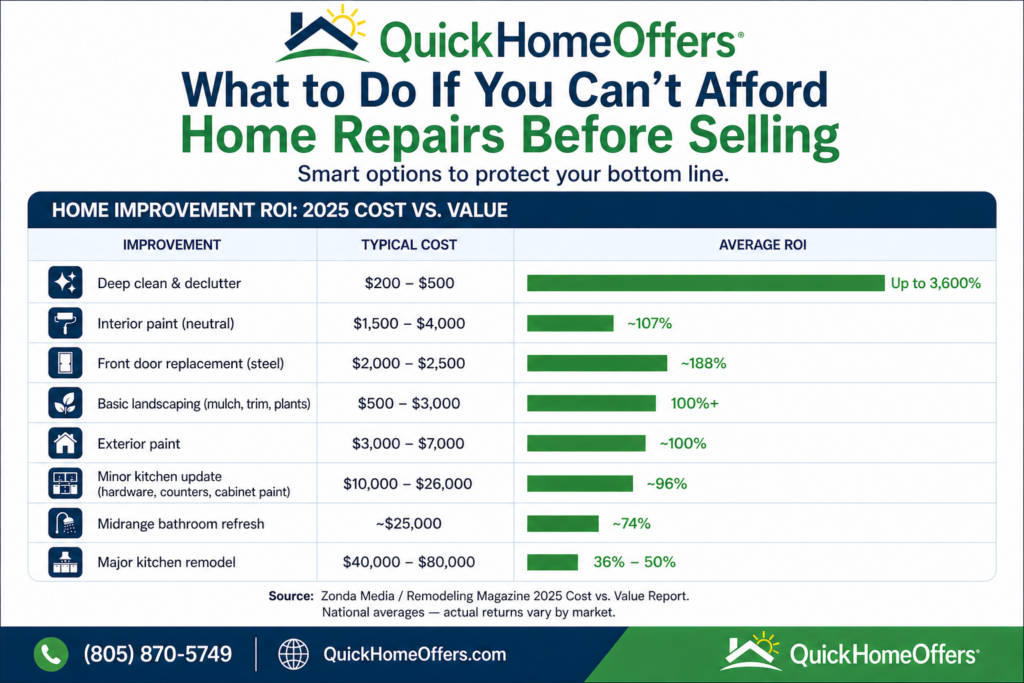
Low-cost improvements help only when the home’s core systems work: the roof holds, the foundation is stable, and the electrical and plumbing function. Then small fixes can change how buyers see the property. Not every improvement is worth the money, though.
Deep cleaning, including cleaning windows and removing excess furniture, makes spaces feel larger and more inviting. Affordable fixes like minor repairs—such as tightening loose handles, patching small holes, or fixing leaky faucets—can often be completed in under an hour and significantly improve buyer perception. When it comes to flooring, normal wear and minor scratches on hardwood floors are generally acceptable and do not require costly refinishing unless there is significant damage. These affordable fixes work because they help traditional buyers see the home as move-in ready — or close to it. When a home shows well, buyers are more likely to make competitive offers and less likely to negotiate steep repair credits after the inspection. Fresh paint and landscaping create a better first impression. That can lead to a faster sale at a higher price.
When to Skip Cosmetic Work Entirely
Cosmetic improvements only make sense when the buyer walking through your door is someone who plans to live in the home. When a home needs a new roof, new plumbing, a full kitchen and bath renovation, or structural work, fresh paint does not raise its value. It raises suspicion. Buyers and inspectors start asking what the seller is trying to hide behind fresh paint on old walls.
If your buyer pool is realistically limited to cash buyers, real estate investors, and house flippers, cosmetic work is almost always wasted money. These buyers are purchasing the property for its bones and its after-repair potential, not its current appearance.
Investors will tear out the flooring, gut the kitchen, and redo the bathrooms regardless of what you do before the sale. We see this constantly — sellers paint the place and install new carpet, expecting a higher offer, but the buyer was going to demo everything anyway. That money would have been better off staying in the seller’s pocket.
If you’re in a situation where you’re behind on payments or facing foreclosure, it’s best to sell as-is because time is your most valuable resource here. Skip pre-sale work so late fees and penalties have less time to pile up.
Before spending anything on improvements, ask yourself two questions: Is the buyer for this home someone who will live in it, or someone who will renovate it? And will the money I spend actually come back to me at closing? If the answer to either question is no, skip the cosmetic work and sell the home in its current condition.
Your Options When You Can’t Afford Repairs Before Selling
When your home needs major repairs, and you do not have the money to fix it, you are choosing between four paths. Each one trades off speed, effort, and how much you walk away with at closing.
Sell As Is to a Cash Buyer Directly
Selling as-is to a cash buyer or investor is the fastest option. There are no repairs, agent commissions, inspections, or lender approval. Closings typically happen in 7 to 30 days. This is the most common choice for homeowners whose properties need extensive repairs that would make the home unfinanceable through traditional lenders. It is also the fastest path with the least financial pressure, but you will usually net less than fixing the place up yourself and listing on the open market. Just make sure you vet the buyer when dealing directly with one. This might include obtaining a proof of funds (POF) or a letter of credit (LOC) from a construction lender. Always call the construction lender to verify the information. Ask about previous projects and referrals from other sellers.
List As Is on the Open Market With an Agent
Listing as-is with an agent reaches more buyers but takes longer and costs more. Price the home from nearby comparable sales, adjusted down for its condition and repair costs. It’s crucial to price your home accurately by factoring in repair needs and current market trends. Obtain repair estimates from contractors before setting your asking price. Buyers and their agents will get their own estimates, and if your price does not reflect the actual scope of work, you will lose credibility and offers. When selling a fixer upper in poor condition, it’s advisable to price the home low to attract investors and flippers.
This path exposes the property to a broader buyer pool, including traditional buyers, investment buyers, and house flippers interested in fixer uppers. The tradeoffs are a longer timeline, typically 30 to 90+ days, and 5% to 6% in commissions. Sales can also fall through after inspection when buyers ask for repair credits you cannot afford. Essentially, you’re paying an agent to find a cash buyer like Quick Home Offers® when there are many who buy direct, putting money back into your pocket.
When taking this route, consider getting a pre-listing inspection to provide transparent disclosures upfront and build trust with potential buyers. Some agents also recommend avoiding the formal “as-is” label in the listing description, as it can signal desperation and invite lowball offers.
Offer Seller Credits or Repair Concessions
A seller credit lets the buyer handle repairs after closing. You list the home, or sell it yourself, and negotiate a repair credit at closing. The credit comes out of your sale proceeds, so you don’t need cash on hand. This works best when the home’s issues are manageable, and the buyer has the appetite to coordinate the repairs. It does not work well when the repairs are extensive or when the property cannot qualify for financing.
Finance the Repairs Before Selling
Financing repairs before listing can make sense if you have enough equity. The repairs also need to be small relative to the price increase they bring. The key question is whether the money you spend on repairs will come back to you — and then some — at closing.
A home equity line of credit (HELOC) lets you borrow against your home’s equity at variable interest rates lower than those of credit cards or personal loans. Most lenders require 15% to 20% equity and a credit score in the mid-600s or higher. You draw only what you need and pay interest only on what you borrow. The downside: your home is the collateral, and expect two to six weeks from application to funding, which may not work on a tight timeline.
A cash-out refinance replaces your existing mortgage with a larger one and gives you the difference in cash. This can make sense if current interest rates are favorable, but if your current rate is significantly lower than today’s rates, you are giving up that rate on the full loan balance just to access repair funds. Run the numbers carefully.
A personal loan or home improvement loan from a bank or credit union is unsecured, so approval is faster — often within days — but interest rates are higher, typically 7% to 15% or more. Repayment periods are usually under 10 years. Personal loans work best when repair costs are in the $5,000 to $25,000 range. Retailers like Home Depot and Lowe’s also offer project financing for smaller jobs like flooring or a water heater, but read the terms closely — promotional rates often jump to 25% or higher if the balance is not paid before the promo period ends.
Some brokerages also offer concierge programs that fund repairs upfront and deduct the cost from your sale proceeds at closing – this is rare, but asking doesn’t hurt. On the buyer side, FHA 203(k) loans allow a buyer to finance both the purchase price and repair costs into a single mortgage, which can expand your buyer pool if the home needs work but is still structurally sound.
Financing repairs only makes sense when two things are true: the cost of the work is modest relative to the increase in sales price, and you have the time to complete it before you need to close. If the home needs $80,000 in work and the market will only reward $40,000 of that in a higher sale, financing is a losing proposition.
Are There Programs That Help Pay for Home Repairs in California?
Yes, some government programs help California homeowners pay for home repairs. Homeowners below their county’s area median income limits may qualify for repair assistance. Some programs require no repayment, and others charge rates far below a bank’s. The USDA Section 504 Home Repair Program lends up to $40,000 at a 1% fixed rate to very-low-income homeowners in eligible rural areas of California. It also offers grants up to $10,000 for homeowners age 62 and older to address health and safety hazards. Loans and grants can be combined for up to $50,000. You can check whether your address qualifies on the USDA eligibility map.
At the state level, California’s CalHome Program funds local agencies to provide rehabilitation loans and grants to low- and very-low-income homeowners. CalHome does not lend directly to individuals. Your city or county housing department administers the funds, so amounts and terms vary by location. Some municipalities offer forgivable loans that require zero repayment if you stay in the home for a set number of years, while others provide grants from $5,000 to $60,000 for critical repairs like roofing, plumbing, electrical, and HVAC. To find programs in your area, call 2-1-1 or contact your city’s housing department directly.
One thing to know: these programs are designed to help homeowners stay in their homes, not to prepare a property for sale. Some come with occupancy requirements that conflict with selling — for example, a forgivable loan that converts to a balance due if you sell within five to ten years. If the repairs your home needs exceed what these programs cover, or the application timeline does not match your need to sell, a direct cash sale may still be the more practical path.
We have sold two properties to Quick Home Offers this year…
We have sold two properties to Quick Home Offers this year, dealing mostly with Adam Justiniano. Adam is very professional and made the entire process smooth both times.
Can’t afford to fix it before selling? You don’t have to.
We’ll Call You Within 1 Business Day
Enter your number. We’ll walk through your options — whether you sell to us or not. No fees. No obligation. Serving California since 2013.
What to Know Before Accepting an Offer
Selling to a cash buyer is the most direct path to closing if your home is unfinanceable or you simply cannot afford the repairs. The basics of how cash sales work and how to vet a legitimate cash buyer are covered in our full as-is selling guide. Most sellers in this situation skip one step they should take: shopping the offer.
Do I Have to Tell Buyers About Repairs I Can’t Afford to Make in California?
Yes. Most sellers of California homes must give the buyer a written statement about the property’s condition (Civil Code §1102). You disclose what you know, so repairs you know are needed belong on it, even if you cannot afford them. Selling “as is” does not change this. California law says any waiver of these disclosure rules is void (§1102(c)).
Some sales are exempt, including probate court sales and foreclosure sales (§1102.2). The statement should reach the buyer as soon as practicable before the sale closes. If it arrives after the buyer signs an offer, the buyer gets three days to cancel. That becomes five days if it was mailed or sent electronically (§1102.3).
What this can mean for you: List every repair you know the house needs, including the ones you are leaving for the buyer. A cash buyer who takes the house as is usually still gets the statement. Every property Quick Home Offers® has closed needed work. Our as-is selling guide covers California’s disclosure forms in more detail.
This is general information, not legal advice. For help with your situation, talk with a California real estate attorney.
Get Multiple Cash Offers Before You Decide
Contact at least three cash buyers before accepting any offer. Ask each one how they arrived at their number, what repairs they are estimating, and whether there are any fees or deductions at closing. A legitimate buyer will be transparent about their math. If someone gives you a number without explaining how they got there, move on.
The right comparison is net to net, not offer price to offer price. A $500,000 cash offer with no commissions, no repairs, and a 14-day close may put more money in your pocket than a $580,000 listing that takes four months, costs 6% in commissions, and ends with $15,000 in buyer-requested concessions after the inspection.
Ask About Creative Sale Structures To Put More In Your Pocket
Most sellers assume a cash sale means one price, one closing, done. Some sale structures can increase what you walk away with, if you have some flexibility.
Seller financing means you act as the lender. Instead of getting a bank loan, the buyer makes a down payment and pays you monthly installments at an agreed interest rate. This can net you significantly more than a straight cash sale because you earn interest on top of the sale price, and it opens your buyer pool to investors and buyers who may not qualify for traditional financing. The tradeoff is that you do not get all your money at once, and you carry the risk that the buyer stops paying. Seller financing works best when you own the property free and clear or have a small remaining mortgage balance, and when you do not need the full proceeds immediately.
A profit-sharing arrangement is another option. In some cases, a cash buyer will fund all repairs and renovations and offer the seller a share of the upside when the property resells — for example, a split on anything above an agreed sale price. This is uncommon. Most investors will not consider it, and it only works on properties where the after-repair value is high enough to justify the risk for both sides. Quick Home Offers® has structured sales this way under the right circumstances, but it is the exception. It is still worth asking — the worst they can say is no.
Not every buyer will entertain creative terms, but you will never know unless you ask. Get your straight cash offers first as a baseline, then ask your top candidates whether seller financing or a profit-sharing structure is on the table.
Protect Yourself No Matter How You Sell
Always close through an independent third-party escrow and title company — never directly with the buyer. If the sale involves seller financing or creative terms, have a real estate attorney review the contract before you sign. Also request a credit report from the buyer. A one-time legal review typically costs a few hundred dollars and is worth every dollar on a six-figure transaction.
Where Quick Home Offers® Buys Houses That Need Repairs in California
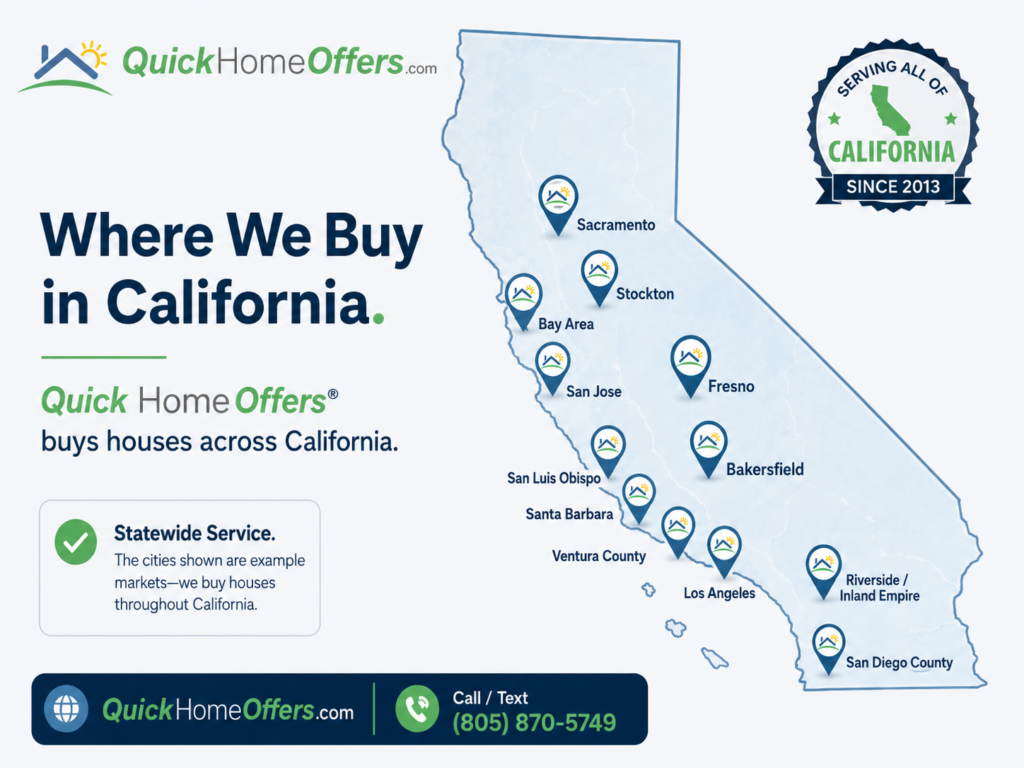
Quick Home Offers® buys houses that need repairs all over California. If you would rather fix the home first, some cities, counties and utilities offer repair help. Some repair loans come due when you sell, which lowers what you take home. Here is what we found in each area we serve.
Who buys houses that need repairs in Kern County?
Quick Home Offers® buys houses that need repairs in Kern County, California. That includes Bakersfield. We have closed 75+ transactions in Kern County since 2013.
Good to know:
- Kern County: CAPK’s free weatherization program can include minor home repairs, for incomes at or below 150% of the federal poverty level.
Who buys houses that need repairs in Santa Barbara County?
Quick Home Offers® buys houses that need repairs in Santa Barbara County, California. That includes Santa Barbara, Santa Maria and Lompoc. Across California, every property we have taken on needed work.
Good to know:
- Santa Barbara County: CommUnify offers free or low-cost energy repairs. That can include a new heater or water heater. It also does small safety repairs for seniors 60 and over.
- City of Santa Barbara: Santa Barbara Clean Energy pays rebates of $2,500, or $3,500 for income-qualified households, to replace a gas water heater or gas furnace with a heat pump.
Who buys houses that need repairs in Los Angeles County?
Quick Home Offers® buys houses that need repairs in Los Angeles County, California. That includes Los Angeles, Long Beach, Lancaster and Palmdale. We cover the seller’s closing costs.
Good to know:
- City of Los Angeles: LADWP offers free energy and water upgrades, and rebates of up to $2,500 for a heat pump water heater.
- Southeast Los Angeles County: The Live Lead-Free program requires keeping the home for three years after the work, so it does not fit if you plan to sell.
Who buys houses that need repairs in Ventura County?
Quick Home Offers® buys houses that need repairs in Ventura County, California. That includes Ventura, Oxnard, Thousand Oaks and Simi Valley. Our company is based in Ventura County. Adam speaks directly to every seller about their situation.
Good to know:
- Oxnard: The city offers 0% home repair loans for health and safety repairs, such as roofing, heating, electrical and plumbing. Call the city’s Housing Department at (805) 385-7400 to ask about available funding.
- Ventura County: Healthy Homes Ventura County offers free lead testing for homes built before 1978. It may also pay for repairs, case by case.
- Ventura County: CAVC fixes unsafe furnaces and water heaters at no cost, as part of its weatherization program.
Who buys houses that need repairs in San Bernardino County?
Quick Home Offers® buys houses that need repairs in San Bernardino County, California. That includes San Bernardino, Fontana, Rialto, Victorville and Hesperia. About 1 in 10 of the properties we have taken on across California had a code violation.
Good to know:
- Fontana: The city offers rehab grants starting at $5,000, and up to $15,000 for all-senior households replacing a roof. Its 0% repair loans of up to $20,000 come due when you sell.
- San Bernardino County: CAPSBC’s weatherization program can repair or replace water heaters and heating and cooling appliances.
Who buys houses that need repairs in Riverside County?
Quick Home Offers® buys houses that need repairs in Riverside County, California. That includes Riverside, Moreno Valley, Corona and Temecula. We pay both sides of escrow and title fees when you sell.
Good to know:
- Moreno Valley: The Beautify MoVal program offers exterior repair grants of up to $15,000.
- City of Riverside: A city rehab loan comes due when you sell.
- Corona: A city rehab loan is forgiven a quarter at a time, at 5, 10, 15 and 20 years, as long as you keep living in the home. If you sell before then, the unforgiven balance is due.
Who buys houses that need repairs in San Diego County?
Quick Home Offers® buys houses that need repairs in San Diego County, California. That includes San Diego, Chula Vista, Oceanside and Escondido. We can make a cash offer within 1 business day.
Good to know:
- City of San Diego: The city’s lead repair program costs owners little or nothing, but it does not take homes with open code violations or work done without permits.
- San Diego County: A county home repair loan must be repaid when you sell.
Who buys houses that need repairs in Sacramento County?
Quick Home Offers® buys houses that need repairs in Sacramento County, California. That includes Sacramento, Elk Grove, Citrus Heights and Rancho Cordova. Across California, most of our sales close in 7 to 30 days.
Good to know:
- Sacramento County: SHRA’s home repair program takes applications when funds are available.
- Citrus Heights: The city offers deferred repair loans of up to $60,000, due when you sell.
- Rancho Cordova: The city’s CalHome program offers zero-interest deferred-payment loans for health and safety repairs. It’s for owner-occupied single-family homes inside city limits, with income limits.
- Sacramento: SMUD pays rebates of up to $3,000 for heat pump heating and cooling and up to $4,000 for heat pump water heaters.
Who buys houses that need repairs in Fresno County?
Quick Home Offers® buys houses that need repairs in Fresno County, California. That includes Fresno and Clovis. We can close in as little as 7 days.
Good to know:
- Clovis: The city offers home repair grants of up to $8,000 or 0% loans. Loan applications are accepted year-round, and a grant can be applied for once every 5 years. A city repair loan is repaid when you sell or transfer the home, and a grant must be repaid if you sell within one year after the repairs are done.
- Fresno County: The county fixes lead hazards at no cost for those who qualify.
Who buys houses that need repairs in San Luis Obispo County?
Quick Home Offers® buys houses that need repairs in San Luis Obispo County, California. That includes San Luis Obispo, Paso Robles and Atascadero. About half of our sales closed remotely, so you can sell from anywhere.
Good to know:
- San Luis Obispo County: CAPSLO does small home repairs at no cost for seniors 60 and over. Its weatherization program repairs or replaces heaters, air conditioners and water heaters for income-eligible homeowners and renters.
We also buy in Solano County, the Bay Area and the rest of the Central Valley. Quick Home Offers® has closed 300+ transactions since 2013 across California. If you can’t afford repairs and want to sell as is, call Adam at (805) 870-5749.
Program funding and rules change, so confirm the details with each program before you apply. This is general information, not financial or legal advice.
Frequently Asked Questions About Selling a Home That Needs Repairs In California
Can I sell my house if it needs major repairs?
Yes. You can sell a home in any condition in California. Roof damage, foundation issues, electrical problems, or other major defects can keep a home from qualifying for traditional financing. If that happens, your buyer pool will be limited to cash buyers and real estate investors. If the home’s issues are cosmetic, you can list it on the open market with a real estate agent and price it to reflect its current condition. Either way, you are legally required to disclose all known material defects to the buyer. Every property Quick Home Offers® has taken on needed work.
What should I not fix before selling my house?
Skip major renovations before a sale. Full kitchen remodels, room additions, and major renovations return only 36% to 50% of their cost. The cheapest projects return the most: a deep clean, decluttering, neutral interior paint, and basic curb appeal. Interior paint alone averages about 107% ROI. Minor kitchen updates like new hardware and painted cabinets can return up to 96%, and a midrange bathroom refresh about 74%.
| Improvement | Typical Cost | Estimated ROI |
|---|---|---|
| Deep clean and declutter | $200–$500 (professional cleaning) | Very high |
| Interior paint (neutral colors) | $1,500–$4,000 | ~107% |
| Exterior paint | $3,000–$7,000 | ~100%+ |
| Front door replacement (steel) | $2,000–$2,500 | ~188% |
| Basic landscaping (mulch, trim, seasonal plants) | $500–$3,000 | 100%+ (5–15% increase in perceived value) |
| Power wash driveway and siding | $200–$500 | High (minimal cost, significant visual impact) |
| Clean or replace windows | $100–$300 (cleaning) / $3,000–$10,000 (replacement) | Cleaning: high / Replacement: ~67% |
| Minor kitchen update (hardware, countertops, paint cabinets) | $10,000–$26,000 | ~96% |
| Midrange bathroom refresh (fixtures, tile, vanity) | ~$25,000 | ~74% |
| Major kitchen remodel | $40,000–$80,000 | 36–50% |
Remodeling ROI figures are national averages from the Zonda Media / Remodeling Magazine 2025 Cost vs. Value Report. Cleaning, landscaping, and power-washing returns are general estimates and vary widely by market, condition, and scope.
If your home needs extensive work and your realistic buyer pool is cash buyers or investors, skip cosmetic upgrades entirely — they are purchasing the property for its potential, not its current appearance, and will redo the work regardless.
Can I borrow money to fix my house before selling?
Yes. A home equity line of credit is the most common option. Most lenders want at least 15% to 20% equity and a credit score in the mid-600s or higher. Personal loans and home improvement loans from banks or credit unions are available without using your home as collateral, though interest rates are higher. Low-income homeowners may qualify for government programs like the USDA Section 504 Home Repair Program, which offers loans at 1% interest and grants up to $10,000 for homeowners 62 and older. Before borrowing, make sure the cost of repairs is modest enough relative to the expected increase in sales price to justify the investment.
What repairs make a house unfinanceable?
The most common issues that block a mortgage are roof leaks, foundation problems, unsafe electrical, major plumbing failures, and a broken HVAC system. Missing flooring, broken windows, and unresolved fire, water, or mold damage also block financing. Another issue that comes up is code violations – active code violations generally must be addressed before conventional lenders will fund.
Lenders also require the buyer to carry homeowner’s insurance, and many insurers will not write a policy on a home with these issues. If the home cannot be insured, it cannot be financed.
Should I sell my house if I can’t afford to fix it?
Sell sooner if the home has health or safety issues you cannot fix. Examples are active mold, faulty wiring, gas leaks, sewage problems, and structural damage that makes the home unsafe. Living in a home with these conditions puts you and your family at risk. The problems typically get worse and more expensive the longer they go unresolved. A cash buyer can close quickly and take on the remediation after closing.
If the issues are cosmetic and the home is safe to live in, you have more time to evaluate your options. Get cash offers first so you have a baseline, then compare what you might net on the open market after commissions, carrying costs, and buyer concessions.
If the house is a rental with tenants in it, see how to sell a tenant-occupied house in California before you decide.
If you want to stay in your home but cannot afford critical repairs, government programs like the USDA Section 504 program and local CalHome-funded rehabilitation programs may be able to help with health and safety repairs at little or no cost. Call 2-1-1 to find what is available in your area.
What is the 30% rule in remodeling?
The 30% rule is a general guideline suggesting you should not spend more than 30% of your home’s current market value on renovations. If your home is worth $400,000, that means capping total renovation spending at $120,000. The idea is that spending beyond this threshold risks over-improving the property relative to comparable homes in your neighborhood. If that happens, you will not recover the full investment at sale.
For sellers who cannot afford repairs in the first place, this rule reinforces the point: if the repairs needed approach or exceed that threshold, selling as is is likely the better financial decision.
What devalues a house the most?
The issues that reduce a home’s value the most are structural and systemic. They include foundation damage, roof failure, outdated electrical and plumbing systems, water damage, and mold contamination. These are the same issues that make a home unfinanceable. Deferred maintenance also hurts value, even when the home is structurally sound. Peeling paint, overgrown landscaping, and cluttered interiors all lead to lower offers. Market conditions and location also play a role, but those are outside your control. The items you can control are condition and presentation.
How do I sell an inherited house that needs repairs in California?
Inherited homes in California often come with decades of deferred maintenance, outdated systems, and personal belongings that need to be cleared out. If the property is in probate, court approval may be required before the sale can close. If you cannot afford the repairs, selling as-is to a cash buyer experienced with inherited homes is typically the fastest path. A cash buyer can purchase the home as-is, handle the cleanout and repairs after closing, and work within the probate timeline. About 1 in 3 of the properties Quick Home Offers® has taken on were inherited or in probate.
About the Authors and Quick Home Offers®
Adam and Josh Justiniano are the founders of Quick Home Offers®, a California statewide cash home buying company. Since 2013, they have closed over 300 California transactions, including single-family homes, multifamily properties, condos, and land. Conditions range from minor cosmetic work to major structural damage, mold contamination, and title complications. Quick Home Offers® buys houses that need repairs across California, including in Fresno, Bakersfield, and Ventura.
Adam speaks directly to every seller about their situation, and Adam or Josh reviews every property before an offer is made. Josh manages marketing, underwriting, and project management for the company’s acquisitions and renovations. Every Quick Home Offers® offer comes from Adam or Josh’s own evaluation. It is never an algorithm, an automated valuation model, or a junior employee reading a script.
If you are considering selling your California property and cannot afford the repairs it needs, we are happy to walk you through your options and provide a no-obligation cash offer. There is no pressure, no fees, and no commitment required.
We have sold two properties to Quick Home Offers this year…
We have sold two properties to Quick Home Offers this year, dealing mostly with Adam Justiniano. Adam is very professional and made the entire process smooth both times.
Call or text us anytime at (805) 870-5749
Or simply enter your number below, and Adam Justiniano will call you back within one business day. We will walk through your options — whether you sell to us or not.
We’ll Call You Within 1 Business Day
Enter your number. We’ll walk through your options — whether you sell to us or not. No fees. No obligation. Serving California since 2013.